

Ollo Credit Card Mobile App

- 184.00 Reviews
- 3.7
- Downloads
- 100,000+
Our take on Ollo Credit Card Mobile App from Appgk
Managing a credit card from a phone can be convenient, but finance apps deserve a more careful look than a typical entertainment download. I spent time with Ollo Credit Card Mobile App as a focused account-management tool from Merrick Bank, paying particular attention to how clearly it presents everyday controls and how much confidence it inspires when handling sensitive financial tasks. My overall impression is practical rather than flashy: this is an app for people who want a direct way to keep an eye on their Ollo credit card, not a complete personal-finance command center.
It is free to download, aimed at Everyone, and belongs to the finance category. The app has reached over 100 thousand installs, with a 3.7 average from more than 300 ratings and over 180 written reviews. Those figures suggest a useful but not universally smooth experience. I would not treat the rating as a final verdict, because banking apps can feel excellent when a particular task works and frustrating when login, verification, or account access becomes difficult. The more helpful question is whether the app fits the way you already manage your Ollo account.
What the app is really for
The central purpose is straightforward: manage an Ollo credit card without relying on a desktop browser or waiting until you are near a computer. That narrow focus is one of its strengths. When I open a card-management app, I want to find the account information and the next useful action quickly. I do not want a feed full of unrelated offers, investment tools, budgeting lessons, or features that distract from the card itself.
That focus also defines its limits. This is not the app I would choose as my only financial organizer if I wanted a combined view of bank accounts, savings, loans, subscriptions, and spending categories. A dedicated budgeting app or a broader banking application may be more suitable for that job. Ollo’s value comes from keeping the credit-card relationship close at hand, especially for users who already have an Ollo account and do not need a wider financial dashboard.
Best Parts of Ollo Credit Card Mobile App
Things to Keep in Mind About Ollo Credit Card Mobile App
The developer shown for the app is Merrick Bank, which gives the product a clear connection to the card issuer rather than making it look like an unrelated third-party tracker. That matters to me in a finance setting. I prefer an issuer-specific application when I am checking card information or taking an account action, because it reduces the need to hand account credentials to another service. Still, the developer name alone is not a substitute for careful login habits, device security, or reading the choices presented during setup.
Trust begins with a narrow purpose
I find the app easier to evaluate because its role is relatively easy to understand. It is not presenting itself as a universal money manager; it is built around the Ollo credit card. That makes the trust question more concrete. I can ask whether the account controls are understandable, whether sensitive moments are handled carefully, and whether I remain in control of decisions instead of being pushed through an unclear flow.
News and Features Related to Ollo Credit Card Mobile App

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
For a cardholder, the most important trust signal is not visual polish. It is knowing what I am about to do before I confirm it. A payment, an account change, or a security step can have consequences beyond the app screen. My advice is to slow down whenever the app asks for confirmation, especially if you are using a new phone, connecting through an unfamiliar network, or reviewing a message that arrived unexpectedly. The safest workflow is to open the app directly rather than following a suspicious message and to verify the account context before continuing.
The app is free, which removes a download fee as a barrier. That does not mean every action connected with a credit card is cost-free, of course, and I would never use the word “free” as a reason to skip the terms of a transaction. The useful distinction is that the application itself does not require a purchase to install. Any account-related charges, payment consequences, or card terms should be considered separately and confirmed inside the appropriate account information.
Don't want to read the full review?
Account controls should be used deliberately
My most practical recommendation is to treat the app as a place for deliberate checks rather than something to glance at casually. Before making a payment or changing an account setting, I would confirm that I am looking at the correct card, review the amount or selection, and pause on the final confirmation screen. This habit is more valuable than trying to complete every task as quickly as possible.
There is also a useful distinction between checking information and taking action. Checking a balance or reviewing account activity is generally a lower-risk interaction than submitting a payment or changing security details. I prefer to separate those moments: first inspect the account, then decide what needs to be done, and only afterward complete the action. That three-step routine helps prevent an accidental tap when I am distracted, commuting, or shopping.
Screenshots
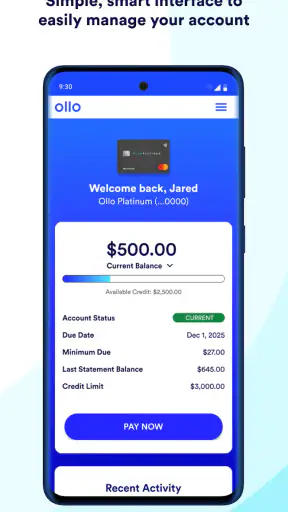
Another good habit is to keep the app updated through the official Android or iOS store rather than downloading modified packages from elsewhere. The current version is 4.49.11, and the listed minimum Android requirement is Android 6.0. That makes the app accessible to many older Android devices, but compatibility is not the same as a guarantee of a perfect experience on every handset. On an older phone, I would pay attention to whether the operating system still receives security updates and whether the device has a screen lock enabled.
Everyday use: a realistic cardholder routine
Imagine I am about to pay for groceries and want to make sure I have enough available credit before reaching the checkout. I would open the app directly, authenticate, check the account information, and close it once I had what I needed. If I then decide to make a payment, I would return to the relevant account area, enter the amount carefully, and review the confirmation details instead of treating the process like a quick calculator.
That scenario shows where the app is most useful: short, purposeful sessions. It can reduce the temptation to postpone a check until later, when a missed detail may become harder to resolve. I also like this workflow for travel preparation. Before leaving home, I can make a habit of checking the card account and ensuring that I know how to access it, rather than discovering a login problem at a hotel desk or restaurant.
The trade-off is that convenience can encourage overconfidence. A phone makes account access feel informal, but the information remains sensitive. I would avoid opening the account on a shared device, would not save credentials where other people can reach them, and would be cautious about public Wi-Fi. These are not special tricks for Ollo; they are sensible boundaries for any credit-card app, and they become especially important when the phone is used for both communication and financial access.
Data-sensitive moments deserve extra attention
Finance apps naturally involve moments where privacy and security matter: signing in, recovering access, confirming identity, reviewing account details, and submitting an account action. I judge those moments by user agency. I want the app to make it clear what it is requesting, why the step is needed, and what will happen after I continue. If a prompt is vague, unexpectedly urgent, or inconsistent with the task I started, I stop rather than trying to work around it.
I also recommend reviewing the app’s permission prompts on your own device instead of automatically accepting every request. Android and iOS show the permissions an application requests, and those choices can vary by operating-system version. I would grant only what is necessary for the function I am actively using, then revisit the device’s app settings later if I want to adjust access. This approach gives me more control than treating installation as a one-time decision.
Privacy is not only about permissions. It is also about what appears on screen when notifications arrive. A phone lock screen can expose financial information to anyone nearby if notification previews are enabled. For a card-management app, I would review notification visibility in the operating system and consider hiding sensitive previews. That small adjustment is easy to overlook, yet it can matter more in daily life than a polished login screen.
When using the app in public, I would also pay attention to shoulder-surfing. A balance or account message can be visible to someone standing beside you, especially on a bright phone display. I prefer to check sensitive information in a private place and to lock the device immediately afterward. These choices do not make the app harder to use; they make the surrounding routine more intentional.
Where user choice matters most
A good account app should let me decide when to inspect information, when to act, and when to stop. I do not want a confusing sequence that makes a decision feel automatic. My preferred approach is to read each screen, use the back button when something looks wrong, and avoid confirming an action until the amount, destination, or account selection matches my intention.
This is particularly important for people who share devices or help a family member with finances. I would not leave the account open for someone else to use, and I would avoid handing over an unlocked phone while the app is displaying account information. If another person needs assistance, I would stay present and complete only the task that was agreed upon. That keeps the cardholder involved instead of turning a convenience tool into an uncontrolled handoff.
Account recovery is another point where patience pays off. If I forget credentials or encounter a verification problem, I would use the app’s normal recovery path and follow the instructions carefully. I would not send passwords, verification codes, or screenshots of account details to someone claiming to provide support through an unsolicited message. If the app cannot resolve the issue, I would use an official Merrick Bank support route rather than relying on a search result or social-media contact.
For users who receive frequent account alerts, notification management can improve both privacy and attention. Too many alerts may cause important messages to blend into routine phone activity, while too few can make it easier to overlook something unusual. I would choose a notification setup that I can realistically monitor, then check the account directly when an alert seems unexpected. The app should support my awareness, not replace it.
How it compares with the usual alternatives
The obvious alternative is using a mobile browser to sign in to the card account. A browser can be preferable if you use several financial institutions and want one familiar access method, or if the app does not behave well on your phone. It may also be more comfortable on a larger screen. The dedicated app’s advantage is convenience: it keeps the card-management task separate from general browsing and is easier to reach for a quick account check.
A second alternative is a general banking or budgeting app. Those tools can be better if your main goal is to see your entire financial situation in one place. They may help you compare spending across accounts or organize a broader budget. The downside is that adding a credit-card account to another service introduces another account connection to manage and another place where financial information is displayed. For someone who only wants access to an Ollo card, that extra layer may not be worth it.
There is also the desktop website option. I would choose a computer when I need a larger display, when I am reviewing several pieces of information at once, or when the phone is unavailable. The mobile app is better for short checks and timely access, but a small screen can make careful review less comfortable. If I am tired, rushed, or dealing with a complicated account issue, I would rather use the interface that lets me read everything clearly.
In other words, this app is not automatically better than every alternative. It is better when the task is specifically tied to an Ollo credit card and I want a direct mobile route. A browser or broader finance tool may be the better choice when I need multi-account organization, a larger working area, or one place to manage several institutions.
Who should use it, and who should skip it
I would recommend the app to an existing Ollo cardholder who wants convenient mobile access and is comfortable treating financial tasks with care. It makes the most sense for someone who checks an account while away from a computer, prefers an issuer-connected tool, and wants a focused experience instead of a full budgeting suite. It is also a reasonable fit for people who appreciate short, task-based sessions and are willing to review security and notification choices on their phone.
I would be more cautious about recommending it to someone looking for a complete money-management system. If you need detailed budgeting, investment tracking, shared household planning, or a consolidated view of many accounts, this app’s card-centered purpose may feel too limited. I would also suggest considering a browser or computer if your phone is old, shared, poorly secured, or difficult to read. Mobile access is helpful only when the device and the surrounding habits are dependable.
The Everyone age rating makes the app broadly available, but that should not be confused with financial suitability for every person. A younger user may still need guidance from a responsible adult when dealing with credit, payments, and account security. The rating describes access to the application, not whether someone understands the consequences of using a credit card.
My cautious verdict after using it
The best reason to choose this app is its direct connection to Ollo card management, not a promise of being an all-in-one financial solution. I appreciate that its purpose is easy to understand and that it can fit naturally into quick routines such as checking an account before a purchase or handling a task away from a computer. The free price and broad device support also make trying it straightforward for eligible cardholders.
My reservations are equally practical. A mobile finance app places sensitive information in a device that may be lost, shared, displayed in public, or exposed through careless notifications. The average rating of 3.7 indicates that the experience is not flawless for everyone, so I would install it with realistic expectations rather than assuming every login or account action will feel effortless. If a task looks unclear, I would stop and use a more comfortable official access route instead of guessing.
For me, the deciding factor is user control. I would keep the phone locked, review permission and notification choices, open the app directly, verify each important screen, and separate information checks from financial actions. Those habits make the application more useful and reduce avoidable mistakes. I would also keep a browser or desktop option available for situations where the mobile screen is too restrictive.
My final recommendation is therefore measured: Ollo Credit Card Mobile App is worth considering if you already use an Ollo credit card and want a focused mobile account tool. It is not the right replacement for a full budgeting platform, and it should not encourage rushed decisions simply because access is convenient. Used deliberately, it can be a sensible part of a cardholder’s routine; used casually on an unsecured or shared phone, the convenience is not worth the risk.
Ollo Credit Card Mobile App FAQ
What is the Ollo Credit Card Mobile App used for?
The Ollo Credit Card Mobile App is designed to help cardholders manage their credit card account from an Android or iOS device. After signing in, users can generally review available credit, check recent transactions, view statements, make payments, monitor account activity, and access important account information without needing to use a desktop browser or contact customer support for every routine request.
How do I log in or register for the Ollo Credit Card app?
To use the app, you normally need an active Ollo credit card account and the login details associated with it. New users may be asked to register by providing identifying information and creating a username, password, or security verification method. If you already have online account access, the same credentials may work in the mobile app. Follow the in-app instructions carefully and avoid sharing verification codes.
Can I pay my Ollo credit card bill through the mobile app?
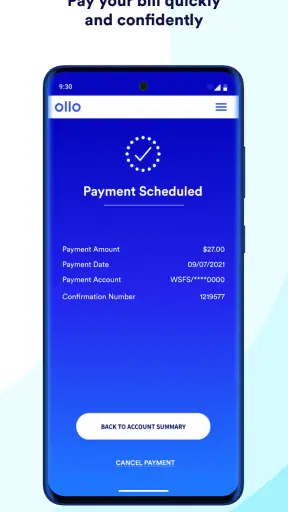
The app is intended to make routine account management easier, including submitting credit card payments when that feature is available for your account. Before confirming a payment, review the selected bank account, payment amount, and scheduled date. Payment processing times can vary, so do not wait until the last moment before the due date. Always verify that the payment was successfully submitted.
What security features does the Ollo Credit Card app offer?
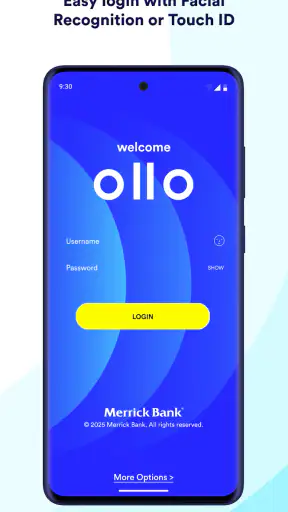
Because the app provides access to sensitive financial information, security should be a priority. Users may be able to protect access with a password, device authentication such as fingerprint or Face ID, and additional verification when logging in from an unfamiliar device. Install the application only from an official app store, keep your phone updated, and contact Ollo promptly if you notice suspicious activity.
What should I do if the Ollo app is not working or I cannot access my account?
If the app will not open, freezes, or rejects your login, first check your internet connection and make sure the application is updated to the latest version. Restarting the device can also resolve temporary problems. If you forgot your credentials, use the official recovery option rather than repeatedly guessing. For locked accounts, payment issues, or suspected fraud, contact Ollo through its verified customer-service channels.











